Damon Boswell opens every in-kind donations engagement at ASAP Grants with a question that exposes how most nonprofits treat donated goods and services. He asks the executive director to estimate the dollar value of the volunteer professional services, donated venue space, and contributed goods the organization received last year. The answers land between 'a few thousand dollars' and 'we don't really track that.' The reality, according to the FASB ASC 958 framework that governs nonprofit accounting, is that contributed services meeting certain criteria must be recognized as revenue at fair value, and donated goods must be recorded at fair market value — which means an organization that does not track in-kind donations is an organization whose financial statements understate its true revenue and misrepresent its true scale. Damon's framing is unsentimental: an in-kind donation is not a freebie. It is revenue, and an organization that treats it as a freebie is an organization whose books do not reflect its actual operations.
In this article, Damon and Ashley Boswell walk through the in-kind donations architecture we build for ASAP Grants clients — the written valuation policy, the fair market value methodology, the FASB ASC 958 recognition criteria, the documentation discipline, and the audit-ready reporting that turns donated goods and services into properly recorded revenue. This sits inside our Fundraising and Reporting & Analytics services, and it is the discipline that separates an organization whose financials tell the truth from one whose financials tell a comfortable lie.
Why 2026 Made In-Kind Accounting Non-Negotiable
The case for rigorous in-kind accounting is no longer aspirational; it is GAAP reality. Under FASB ASC 958-605, nonprofits must recognize contributed services as revenue when those services create or enhance a nonfinancial asset, or when they require specialized skills, are provided by someone possessing those skills, and would typically need to be purchased if not donated. The HBK CPA guidance is explicit that contributed services are recorded in an organization's financial statements when they meet the recognition criteria established by GAAP. The McDonald Jacobs reporting on FASB's gifts-in-kind standard reinforces the point: a nonprofit must report gift-in-kind donations as a separate line item in its statement of activities, apart from contributions of cash. An organization that buries in-kind gifts inside general contributions, or omits them entirely, is an organization whose financial statements fail to meet the standard a sophisticated funder or auditor applies — and the failure is not theoretical, because the understated revenue distorts every ratio a funder uses to evaluate organizational health.
Ashley frames the shift for every board we work with: the question is no longer whether to record in-kind donations. The Adams Brown CPA guidance is direct — in-kind donations must be valued at fair market value and recorded as revenue to stay compliant and avoid reporting issues. A nonprofit that receives $40,000 in donated venue space, $25,000 in pro bono legal services, and $15,000 in donated food but reports only its cash revenue has understated its true revenue by $80,000, and a funder comparing that organization to a peer of similar scale will conclude the peer is twice the operation — when the truth is the in-kind reporting, not the organizational capacity, is the difference. Damon's rule is that the financial statement is the document a funder trusts, and a financial statement that omits in-kind revenue is a financial statement a funder cannot compare to anything, because the comparison is built on incomplete numbers.
The ASAP Grants In-Kind Architecture
Damon builds every in-kind program around a five-layer architecture that moves an organization from ad-hoc gratitude to audit-ready recognition. Each layer has a purpose, because an in-kind process without structure is a process that depends on whoever happens to remember to write down the donation — and memory is not an accounting system.
1. The Written Valuation Policy
The first layer is the one most organizations lack entirely, and Ashley treats it as the foundation that makes every subsequent decision defensible. The Mission Edge guidance recommends creating a written in-kind donations policy, training staff on valuation requirements, and maintaining templates for documentation. The policy specifies what the organization counts as in-kind, how fair market value is determined, who is authorized to value a donation, and what documentation is required for recognition. The NetSuite best-practices guidance reinforces the point — a repeatable process for determining fair market value is the core of compliant in-kind accounting. Damon's rule is that a valuation that is not written down is a valuation that cannot be defended at audit, and a valuation that cannot be defended at audit is a valuation that gets reversed — which means the revenue disappears from the books and the organization's financial picture changes after the fact.
2. The Fair Market Value Methodology
Once the policy exists, Damon builds the fair market value methodology that gives every donation a defensible number. The Double the Donation guidance recommends implementing a standardized valuation process, including checking the price of the same or similar items online — the 'comps' approach. For donated goods, fair market value is the price the item would sell for in its current condition, established through comparable listings, vendor quotes, or appraisals for high-value items. For contributed services, fair value is what the organization would pay for the same service in the open market, documented through the provider's normal billing rate. The MJCPA guidance recommends establishing a policy defining transactions as purchases and formulating clear rules for identifying and verifying exceptions. Ashley's rule is that the valuation methodology is not a guess — it is a documented process that produces a number an auditor can trace from the donation receipt to the financial statement, because a number that cannot be traced is a number that gets challenged.
3. The FASB ASC 958 Recognition Criteria
This is the layer where most organizations either over-recognize or under-recognize, and Damon treats it as the discipline that separates compliant reporting from audit findings. The Aplos guidance on FASB ASC 958 is explicit — the organization must properly recognize cash contributions and also determine the fair value of donated services, recording them appropriately. The recognition criteria for contributed services are specific: the service must create or enhance a nonfinancial asset (such as a volunteer architect designing a building), or it must require specialized skills, be provided by someone possessing those skills, and would typically need to be purchased if not donated (such as pro bono legal, accounting, or medical services). General volunteer time — stuffing envelopes, serving food, setting up chairs — does not meet the recognition criteria and is not recorded as revenue, though it may be disclosed. Damon's framing is that the criteria are not a barrier to recognition; they are the boundary that makes recognition defensible, and an organization that recognizes everything overstates its revenue while an organization that recognizes nothing understates it.
4. The Documentation Discipline
Ashley builds documentation into every in-kind transaction, because the valuation is only as good as the paper behind it. The Mission Edge guidance recommends maintaining templates for documentation, and the Adams Brown CPA guidance reinforces that proper documentation is what makes the valuation audit-ready. For every recognized in-kind donation, the file contains a donation receipt or acknowledgment, the donor's description of the goods or services, the valuation methodology and source (comparable listing, vendor quote, billing rate), the name and qualifications of the person who performed the valuation, and the journal entry recording the revenue and corresponding expense or asset. The Dean Dorton guidance notes that nonprofits are required to disclose a breakout of the amount of in-kind gifts recognized within the statement of activities by category. Damon's rule is that documentation is not bureaucracy — it is the evidence that turns a donated good into recorded revenue, and a donation without documentation is a donation that does not exist on the books.
5. The Audit-Ready Reporting
The final layer is the one that determines whether the in-kind program survives scrutiny, and Damon insists on it for every engagement. The McDonald Jacobs guidance is explicit that gift-in-kind donations must be reported as a separate line item in the statement of activities, apart from contributions of cash, and the Dean Dorton guidance requires disclosure of the breakout of in-kind gifts by category. The reporting layer produces the separate line item, the category disclosure (goods versus services versus use of facilities), and the footnote describing the valuation methodologies used. An organization that records in-kind revenue but does not report it as a separate line item has technically complied with recognition but failed on presentation — and the failure is visible to any auditor or sophisticated funder who reads the statement. Ashley's rule is that the report is the product, and an in-kind program that does not produce a clean, separate, disclosed line item is a program that does the work but does not show the result.
An in-kind donation is not a freebie. It is revenue — and revenue that is not recorded is revenue that does not exist on the books, no matter how real it was in the warehouse. — Damon Boswell
The Three In-Kind Failures
Damon closes every in-kind engagement by naming the three failures that sink in-kind accounting even when the donations are genuine.
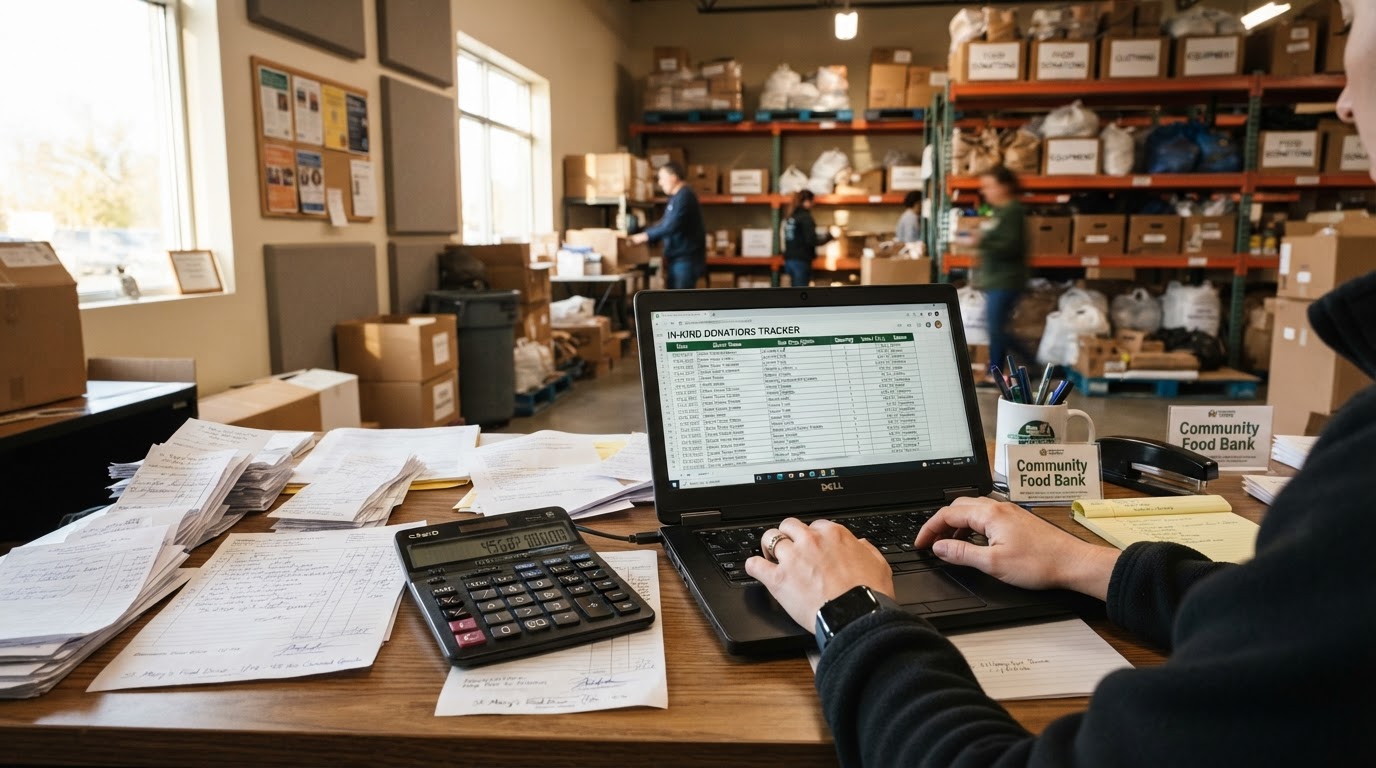
- The no-tracking failure: the organization receives donated goods and services throughout the year, thanks the donors warmly, and never records a dollar of it. The financial statements understate revenue, the audit risks a finding, and the organization's true scale is invisible to every funder who reads the numbers. A donation that is not tracked is a donation that does not count — and a nonprofit that does not count its in-kind revenue is a nonprofit whose books do not reflect its actual operation.
- The guess-valuation failure: the organization records in-kind donations but values them by feel — 'that looks like about five thousand dollars of food' — without a documented comparable, vendor quote, or appraisal. The valuation is challenged at audit, reversed, and the revenue disappears from the books after the fact. A valuation without a source is a valuation without a defense, and a valuation without a defense is a valuation that does not survive review.
- The recognition-error failure: the organization either recognizes general volunteer time that does not meet the FASB ASC 958 criteria, overstating revenue, or fails to recognize specialized professional services that do meet the criteria, understating revenue. Both errors distort the financial picture, and both are the product of not understanding the recognition standard that governs when a contributed service becomes recorded revenue.
Why In-Kind Revenue Changes the Funder Conversation
The most common in-kind failure Ashley sees is not a lack of generosity — the donations are real and the gratitude is genuine. The failure is the assumption that a donation that was not paid for in cash does not belong on the books, which is the assumption that turns a $500,000 operation into a $420,000 operation on paper and makes the organization look smaller than it is. A funder evaluating capacity looks at total revenue, and an organization that reports $420,000 when its true revenue including in-kind is $500,000 is an organization that appears to operate at a scale below its actual reach — which affects every capacity-based funding decision a funder makes. Damon's rule is that the financial statement is the organization's public face to the funding community, and a financial statement that omits in-kind revenue is a face that understates the organization's true capacity and true community support.
This is also why Damon treats in-kind accounting as a fundraising discipline, not just a compliance exercise. The organization that can demonstrate, through properly recorded and reported in-kind revenue, that it has secured $80,000 in donated goods and professional services is an organization that shows funders it has community leverage — that every dollar of cash goes further because the community is contributing alongside it. Funders want to fund organizations that the community already supports, and in-kind revenue is the evidence of that support. An organization that builds in-kind recognition into its accounting builds that evidence into its financial statements, and an organization that does not is leaving the strongest community-support argument it has unmade.
Record What the Community Gives
If your organization receives donated goods, professional services, or use of facilities and does not track, value, and report them as revenue, the problem is not your generosity. The problem is the absence of an in-kind accounting system that turns donated support into recorded revenue. Damon and Ashley Boswell build complete in-kind donation programs — written valuation policy, fair market value methodology, FASB ASC 958 recognition criteria, documentation discipline, and audit-ready reporting — as part of ASAP Grants' Fundraising and Reporting & Analytics services. Schedule a free consultation, and let us build the in-kind system that records what your community gives and reports it the way the standard requires.
Damon & Ashley Boswell
Founding Partners, ASAP Grants
Ashley & Damon Boswell are the founding partners of ASAP Grants, a nationwide professional firm specializing in 501(c)(3) formation, grant writing, and holistic fundraising for nonprofits. Since 2010, they have maintained a 100% success rate on nonprofit filings and helped organizations across all fifty states secure sustainable funding.